
How Much Deposit Should You Pay A Bathroom Fitter?
Luxury Bathrooms Exeter
Somewhere between agreeing a quote and watching the first tile go on, you will be asked for money. This is the part of a bathroom project that gets almost no attention in the magazines, and it is the part where things go genuinely wrong for people - not a grout colour they regret, but thousands of pounds handed to someone who then stops answering the phone.
The good news is that the rules of a fair payment arrangement are simple, they are well established, and a decent firm will not be offended when you insist on them. In fact the way a fitter reacts to a question about payment terms tells you more about them than their portfolio does.
So here is the whole subject laid out: what a normal deposit is, how the rest of the money should be released, which requests should make you walk away, and the legal protections you already have without knowing it.
A normal deposit, and what it actually pays for
For a full bathroom renovation, a deposit somewhere between ten and twenty five per cent of the contract value is the ordinary range. On a project worth twelve to fifteen thousand pounds, that means roughly £1,500 to £3,500 changing hands before anyone lifts a tool.
That money has two legitimate jobs. The first is materials: sanitaryware, brassware, tiles and shower glass are ordered weeks ahead, some of it made to order, and the firm carries that cost until your job starts. The second is the diary. A good fitter books out weeks in advance, and your deposit is what makes it rational for them to turn other work away and hold your slot. It is the same reason we take a commitment before the detailed drawing stage of our own design process - the deposit buys certainty in both directions.
What a deposit is not is working capital for someone else’s previous job. A firm that needs your money to finish the customer before you is a firm running on fumes, and the polite phrase for what happens next is a cash flow failure. The size of the deposit is your best clue: the closer it creeps to half the contract value, the more likely it is funding something other than your bathroom.
Staged payments are the structure that protects everyone
After the deposit, the rest of the money should be released in stages, and each stage should be tied to work you can stand in the room and see. A typical shape for a three to four week renovation looks like this: the deposit on signing, a stage payment once strip-out and first fix are complete, perhaps another once tiling is done, and the balance on completion.
The principle underneath it matters more than the exact percentages: you should always be paying for work that has already happened, never for work that has not. If the firm walked off site tomorrow, the money you have handed over should roughly match the value sitting in your house - the goods delivered and the labour done. When that is true, neither side is carrying the other, and neither side has a reason to feel nervous.
Put the stages in writing before the job starts, in the quote or the contract, with a plain description of what triggers each one. “Second payment due at completion of first fix plumbing and electrics” is a trigger you can verify. “Second payment due week two” is not, because week two arrives whether or not the work has.
The requests that should stop you cold
A handful of payment patterns turn up again and again in the cases that end badly, and they are worth naming plainly.
The first is the large upfront demand - half the job or more before starting. Whatever the stated reason, you are being asked to carry all the risk, and there is no version of a healthy business that needs that. The second is the cash discount. An offer to knock money off for cash is rarely generosity; it usually means the job will not exist on paper, and if the job does not exist on paper, neither does your guarantee, your invoice, or your evidence if anything goes wrong.
The third is urgency. A price that is only available if you pay a deposit today is a sales tactic with a long and ugly history, and legitimate firms in this trade simply do not price that way - a written quote should hold for weeks. And the fourth is the drip: a fitter who keeps coming back mid-job asking for the next payment early, ahead of the agreed trigger. One early request might be innocent. A pattern of them is the sound of a business borrowing from you.
None of these automatically mean you are dealing with a rogue. All of them mean you should slow down and ask more questions, and any two together mean you should probably keep looking.
The cancellation right most people have and never use
Here is something most homeowners never find out about. If you agreed the contract in your own home - which is how almost every bathroom job is sold, since the fitter comes to you to survey and quote - the Consumer Contracts Regulations give you fourteen days to cancel, without giving a reason, and get your deposit back. The trader is required to tell you about this right in writing; if they never mention it, that period can extend by months, and their failure to tell you is itself a breach. Citizens Advice has a clear guide to cancelling a service that walks through exactly how it works.
There is one wrinkle. If you want the work to start inside those fourteen days, the firm should ask you to confirm that in writing, and you then owe for whatever has been done if you cancel partway. That is fair on both sides. But the practical use of the cooling-off period is quieter than cancellation: it takes the pressure out of signing. You can commit on the day, sleep on it, and know that nothing is irreversible for a fortnight. Anyone who tries to make you feel that signing is a cliff edge is ignoring the law that says it is not.
Alongside that sits the Consumer Rights Act, which requires any trade work to be carried out with reasonable care and skill. You do not need to negotiate that protection into a contract. It is already there.
Pay the deposit by credit card if you possibly can
How you pay matters nearly as much as how much. If any part of the job costs more than £100 and you pay any of it on a credit card - even just a slice of the deposit - Section 75 of the Consumer Credit Act makes the card company jointly responsible with the trader for the whole contract. Firm goes bust with your money? Work never done? You can claim from the card issuer. Which? explains Section 75 in full, and it is the single strongest consumer protection in this whole area.
Some smaller firms do not take cards, and a bank transfer to a verified business account is normal in the trade - but understand that a transfer carries no equivalent protection, which is exactly why the staged structure above matters more when you pay that way. Debit cards sit in between: no Section 75, but a chargeback scheme that can sometimes recover money. Cash sits at the bottom, unprotected and unprovable, which is the real reason to refuse the cash discount however tempting the number.
The last payment is your only leverage - spend it slowly
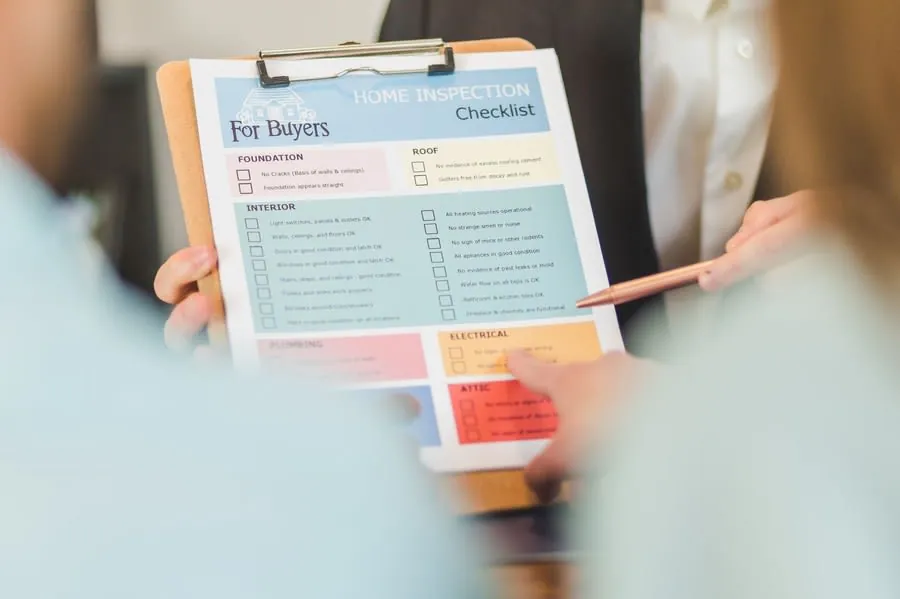
Every bathroom, including a well-fitted one, finishes with a snag list. A door that needs adjusting after the room has been steamy for a week, a bead of silicone to redo, a loose end of trim. This is normal, and the mechanism that gets it dealt with promptly is the final payment. Once the last invoice is settled, you are relying on goodwill; while a sensible balance is outstanding, you are relying on incentive. Agree up front that the closing payment follows a walk-through together and completion of the snags, and a good firm will say yes without hesitation, because good firms plan to snag anyway.
Which brings this back to where it started: payment terms are a character test you get to run before hiring anyone. Around Exeter you can also check whether a firm is vetted through Buy With Confidence, the trading standards approval scheme that Devon’s councils helped found, which audits members rather than just collecting reviews. Pair that with the eight questions in our guide to choosing a bathroom fitter in Exeter and the payment structure in this one, and you have covered the two ways a project actually fails - the wrong firm, and the wrong terms.
Common questions
How much deposit is normal for a bathroom renovation?
Between ten and twenty five per cent of the contract value is the ordinary range, reflecting materials ordered ahead and a committed slot in the diary. Be wary as it approaches a third, and treat a demand for half or more upfront as a reason to walk away.
Is it safe to pay a bathroom fitter in cash?
It is legal, but it is the least protected way to pay: no Section 75 cover, no chargeback, and often no paper trail. A cash discount usually signals a job that will not be invoiced, which also puts your guarantee in doubt. Pay by credit card or bank transfer against a written invoice instead.
Can I get my bathroom deposit back if I change my mind?
Usually, yes, if you act quickly. Contracts agreed in your home carry a fourteen day cooling-off period under the Consumer Contracts Regulations, during which you can cancel without a reason and be refunded. If work has started at your written request, you pay for what has been done and recover the rest.
Should I pay the final invoice if there are still snags?
Not in full. The accepted approach is a joint walk-through, a written snag list, and the final payment released when the list is cleared. A professional firm expects this. Withholding a sensible balance is not hostile - it is how completion is defined.
What if a fitter wants the whole cost upfront?
Decline, whatever the justification offered. Full payment before work starts removes every incentive that protects you and is the single most common feature of jobs that end in trading standards complaints. No reputable bathroom firm prices this way.